
Sage & Main helps business owners fund their succession plan, close the gaps in their buy-sell agreement, and restore the protection their top people quietly lose to group-plan caps.
THE EXPOSURE MOST PLANS MISS
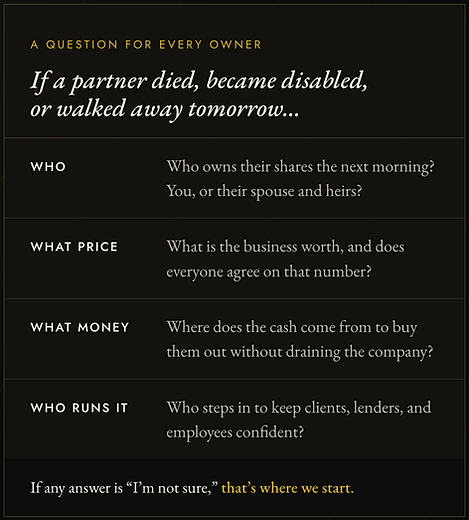
Everyone plans for death. Almost no one plans for the stroke you survive.
Most business owners with a succession plan have some life insurance behind it. Far fewer have addressed disability, even though an owner is more likely to become disabled during their working years than to die.
Medicine has come a long way. People recover from strokes, heart attacks, and serious accidents. But recovering and being able to run the company again are two different things. When an owner can’t return, the business is left paying a partner who can’t work, or trying to buy them out from cash flow.
You don’t need to insure every dollar.
You do need a plan for both death and disability.

WHAT WE DO
Four ways we protect a business and its people.
BUSINESS CONTINUITY
Succession & buy-sell funding
Make sure ownership changes hands the way you intend, at a fair price, with the money already in place when a partner dies, becomes disabled, or retires.
Buy - Sell Life Funding
Buy - Sell Disability Buyout
Key Person Life and Disability
ESOP Repurchase Funding
Exit and Retirement Strategies
BENEFIT RESTORATION
Close the group-plan gap
Group life and disability plans are built for the average employee. We layer guaranteed-issue coverage on top for your highest earners, often with no medical exams, so their protection matches their actual pay.
Group Life Carve Out
Excess Life
Group DI Carve Out
Excess IDI
Exit and Retirement Strategies
Each starts with a review of what you already have. We only recommend what closes a real gap.
HIGH-LIMIT DISABILITY
Disability buyout & income protection
U.S. carriers typically cap disability buyout coverage at a few million dollars per owner. Through our specialty-market partners, including select Lloyd’s of London syndicates, we can place coverage well beyond those limits for owners, executives, and high earners.
Disability Buyout
Key Person Disability
High-Limit Income Protection
Excess Individual DI
KEY EMPLOYEE RETENTION
Executive benefits
Recruit, reward, and keep the people you can’t afford to lose, with benefits you can offer selectively and tie to performance and time with the company.
Non-qualified Deferred Comp
SERP
Stay Bounuses
Long Term Incentive Plansts
Excess IDI
Split Dollar
Section 182 Executive Bonus
Also available: Cash balance plans Balance-sheet strategies with corporate-owned cash value
Fast, short-term coverage for loans, acquisitions, and estate plans in progress
BUY-SELL AGREEMENTS
A buy-sell agreement is a will for your business.
It decides who can own the company, what their shares are worth, and how a departing owner gets paid. That last part is where most agreements fall short. A document is a plan on paper. It doesn’t fund itself.
We make sure there is money behind every trigger in it.
What we look at in a Buy-Sell Review
Bring your agreement and any policies behind it. We’ll show you where it holds up and where it doesn’t.
Is the valuation current, or set years ago when the company was worth far less?
Is the agreement funded for disability, or only for death?
Does the coverage still match each owner’s share of today’s value?
Is it structured the right way: cross-purchase, entity redemption, or a hybrid?
Do the disability definitions in the agreement match the policies?
What happens at retirement, divorce, or a voluntary exit?
Death
Without a funded agreement, a partner’s spouse or heirs can inherit their stake and become your new co-owner.
Disability
MOST OFTEN UNFUNDED
The company keeps paying an owner who can’t work, or buys them out from cash flow it needs to operate.
Retirement
No agreed price, no timeline, and no money set aside. The business you planned to retire on becomes hard to sell at full value.
Divorce
An ex-spouse’s claim on company shares can trigger a court-ordered valuation and an unwanted owner.
Departure
A partner who leaves can take clients and key staff, with no agreed terms for buying back their interest.
Outside Offers
A buyer, lender, or private equity firm will ask how ownership transfers. Without an answer, the deal slows or stalls.
BENEFIT RESTORATION
Your group plan was built for the average employee.
A 60% disability benefit sounds generous until it hits the monthly cap. The higher someone’s pay, the smaller the share of it their group plan actually protects. Most employers don’t realize this is happening. Try your own numbers below.
Guaranteed issue
For qualifying groups, coverage is issued without medical exams or financial underwriting. Employees generally need to be actively at work full time.
Selective and portable
You choose who participates. Policies can be owned by the employee and go with them, with premiums locked in at issue.
What We Need
Your group LTD and life benefit booklets and a census with titles and total compensation. We return a complete exposure analysis at no cost.
EXECUTIVE BENEFITS
Your group plan was built for the average employee.
Your highest earners can only defer a small slice of their pay into a 401(k). Your competitors are trying to hire them. Losing one senior leader can cost twice their salary to replace, before counting lost clients and projects.
Nonqualified plans let you reward the people you choose, in amounts you choose, and tie it to staying.

PREMIUM FINANCING WITH SUCCESSION CAPITAL
Fund large coverage without tying up your capital.
When a business or estate is worth tens of millions, the right amount of permanent life insurance can carry a large premium. Premium financing lets a bank pay most of that premium while your money stays invested in the business, your real estate, or your portfolio.
You pay the loan interest and pledge collateral. The policy builds cash value and a death benefit that can grow over time, and you can switch to paying cash later if that makes more sense.
A buy-sell that outlives the business
One permanent policy funds the buyout today. If the company is sold, the same policy becomes liquidity for estate taxes instead of lapsing like term insurance.
Estate taxes and
fairness between heirs
Cash at the right time, so heirs don’t have to sell the business or real estate to pay the estate tax, and the child who isn’t in the business still receives a fair share.
Put existing policies to work
Cash value in policies you already own can serve as collateral, which lowers the out-of-pocket cost of adding the coverage you need now.
How we approach it
We always show financing side by side with paying cash, so you can compare.
It isn’t free insurance. We plan for interest to be paid, generally for at least the first ten years.
Lenders stress-test every case assuming zero policy growth and rising interest rates, so you see the hard scenario before you sign.
The plan is reviewed every year. You can adjust payments, add collateral, or move to paying cash.
Is it a fit?
Premium financing is generally worth considering for owners and families with about $15 million or more in total net worth, counting business interests and real estate. Strong income can make room for less.
We partner with Succession Capital Alliance, a premium financing specialist that works with Lion Street firms and leading life insurance carriers. They design, finance, and service each case with us every year, not just at the start.
WHO WE SERVE
Businesses where one person’s absence changes everything.
Owners with partners
Two or more owners with real value in the company and an agreement that hasn’t been looked at since it was signed.
Professional services firms
CPA, law, medical, engineering, and advisory firms where the revenue walks out the door with the partners.
A CPA firm with 14 shareholders and 19 key employees covered all 25 people with guaranteed-issue life insurance, without underwriting each one individually.
Real estate & development companies
Brokerages, builders, and integrated firms that buy, build, sell, and manage. Value grows fast, and agreements fall behind.
One integrated real estate firm had already budgeted $300,000 a year in its buy-sell agreement to fund partner disability coverage. A market review brought the renewal down from $350,000 to $294,000.
Companies preparing for a transaction
Owners planning a sale, bringing in private equity, or closing on a large loan. Lenders and buyers often require key person coverage, sometimes on short notice.
For deals and loans that can’t wait, short-term coverage can often be put in place within days while permanent coverage is underwritten.
HOW IT WORKS
A review first. Recommendations only if there’s a gap.
01
Conversation
Thirty minutes on the business, the owners, and what you want to happen if something changes.
02
Review
We read your buy-sell agreement, group benefit booklets, and existing policies.
03
Findings
A plain-English summary of where you’re covered, where you’re exposed, and what it would cost to fix.
04
Design
We bring in the right specialists and insurance markets and build coverage that fits the business.
05
Keep it Current
As the business grows, coverage and valuation are reviewed so the plan keeps pace.
WHY SAGE & MAIN
Built by business owners, for business owners.
We've Built Companies
Before this, Luke Lyles and JT Hardcastle started businesses from nothing, made payroll, and took real risk. We know what an owner has on the line because we’ve had it on the line ourselves.
One Place For The Whole Picture
Buy-sell funding, disability, benefits for your top earners, and retention plans usually come from different agents, if they’re handled at all. We look at all of it together, so nothing falls through the cracks.
A Deep Bench Behind Us
We work with Lion Street’s Corporate & Business Solutions team and specialty markets, including Lloyd’s of London, to solve cases most local advisors can’t place.

Sage is the wisdom to plan for what could go wrong. Main is the main thing: what you’ve built, and the people who depend on it. We’re guides, not salespeople. If you decide not to act, you’ll still know exactly where you stand.
FOR CPAs, ESTATE PLANNING ATTORNEYS, & P&C FIRMS
Your client has a buy-sell agreement. Is it funded?
You drafted the agreement or prepared the valuation. We make sure the money is there when a trigger hits, including disability, the one most agreements leave empty.
Bring us in when
A business owner’s death or disability over $2–3 million would cripple the company
A client’s buy-sell hasn’t been reviewed in three or more years
An owner can’t qualify for coverage in U.S. markets, or needs it faster

Business succession, buy-sell funding, disability, and executive benefits for business owners in Dallas–Fort Worth and beyond.
SERVICES
Disability & benefit restoration
Executive benefits


Sage & Main is an independent firm in strategic partnership with Lion Street. Insurance products are offered through licensed insurance agents and are subject to underwriting, carrier approval, and state availability. Specialty-market coverage is placed through licensed intermediaries. Case examples are hypothetical or drawn from our partner network and are not a guarantee of results. Sage & Main does not provide tax or legal advice; consult your CPA and attorney. © 2026 Sage & Main. All rights reserved.